Good personal finance tips rarely involve complicated math. They involve a few repeatable systems that run in the background while you live your life. This article lays out a 30-day plan you can follow in 2026, one small step per week, with examples you can copy today.
No guaranteed returns here, and no get-rich claims. Just practical moves that reduce stress and give your paycheck a clear job.
Why Personal Finance Tips Fail (and What Works Instead)
Most advice fails because it asks for willpower every day. Willpower runs out. Systems do not. The goal is to automate the right choices so that you decide once and then let the plan run.
Three principles guide everything below:
- Automate first. Pay your future self before you see the money.
- Measure lightly. Track only a few numbers.
- Adjust monthly. Small corrections beat dramatic overhauls.
Week 1: Map Your Real Numbers
Before you change anything, learn where you stand. Pull the last three months of bank and card statements and sort every charge into broad buckets.
The four numbers to know
- Monthly take-home income.
- Fixed costs such as rent, insurance, utilities, and loan payments.
- Variable costs such as groceries, fuel, and dining out.
- Total debt and its interest rates.
A tip many people overlook: count irregular costs, such as annual insurance premiums or car repairs, and divide them by twelve. That monthly “sinking fund” figure prevents surprise bills from wrecking your plan.
Week 2: Build a Budget You Can Keep
A budget works only if it fits your life. Here is a comparison of three popular styles.
| Method | How It Works | Best For |
|---|---|---|
| 50/30/20 | Needs, wants, and savings split by percentage | Beginners who want simplicity |
| Zero-based | Every dollar is assigned a job | Detail-oriented planners |
| Pay-yourself-first | Save a fixed amount, spend the rest freely | People who hate tracking |
If you are unsure, begin with pay-yourself-first. Set an automatic transfer on payday, then spend what remains without guilt. You can always add detail later.
For more in-depth walkthroughs and beginner-friendly explainers, browse these personal finance tips on categories, accounts, and everyday money choices.
How Much Should You Keep in an Emergency Fund?
A common target is three to six months of essential expenses, though your number depends on job stability, dependents, and health. Start smaller. A first goal of one month of bills already protects you from many common shocks, such as a car repair or a short gap between jobs.
Where to park the fund
Keep it somewhere safe and accessible, such as a high-yield savings account at an insured institution. The Federal Deposit Insurance Corporation explains how deposit insurance works, including coverage limits per depositor, so you can confirm your cash is protected.
- Name the account “Emergency Only” to discourage dipping in.
- Set an automatic weekly deposit, even if small.
- Refill it first after any withdrawal.
Week 3: Tackle Debt With a Clear Order
Debt feels heavy because it is vague. Make it concrete by listing each balance, rate, and minimum payment. Then choose a payoff approach.
Avalanche versus snowball
The avalanche method targets the highest interest rate first and usually costs less overall. The snowball method targets the smallest balance first and delivers quick wins that keep many people motivated. Both beat inconsistent payments. Choose the one you will actually stick with.
- Pay minimums on everything.
- Send every extra dollar to your target debt.
- When it is cleared, roll that payment into the next one.
- Avoid adding new balances while you pay down old ones.
Week 4: Put Technology to Work
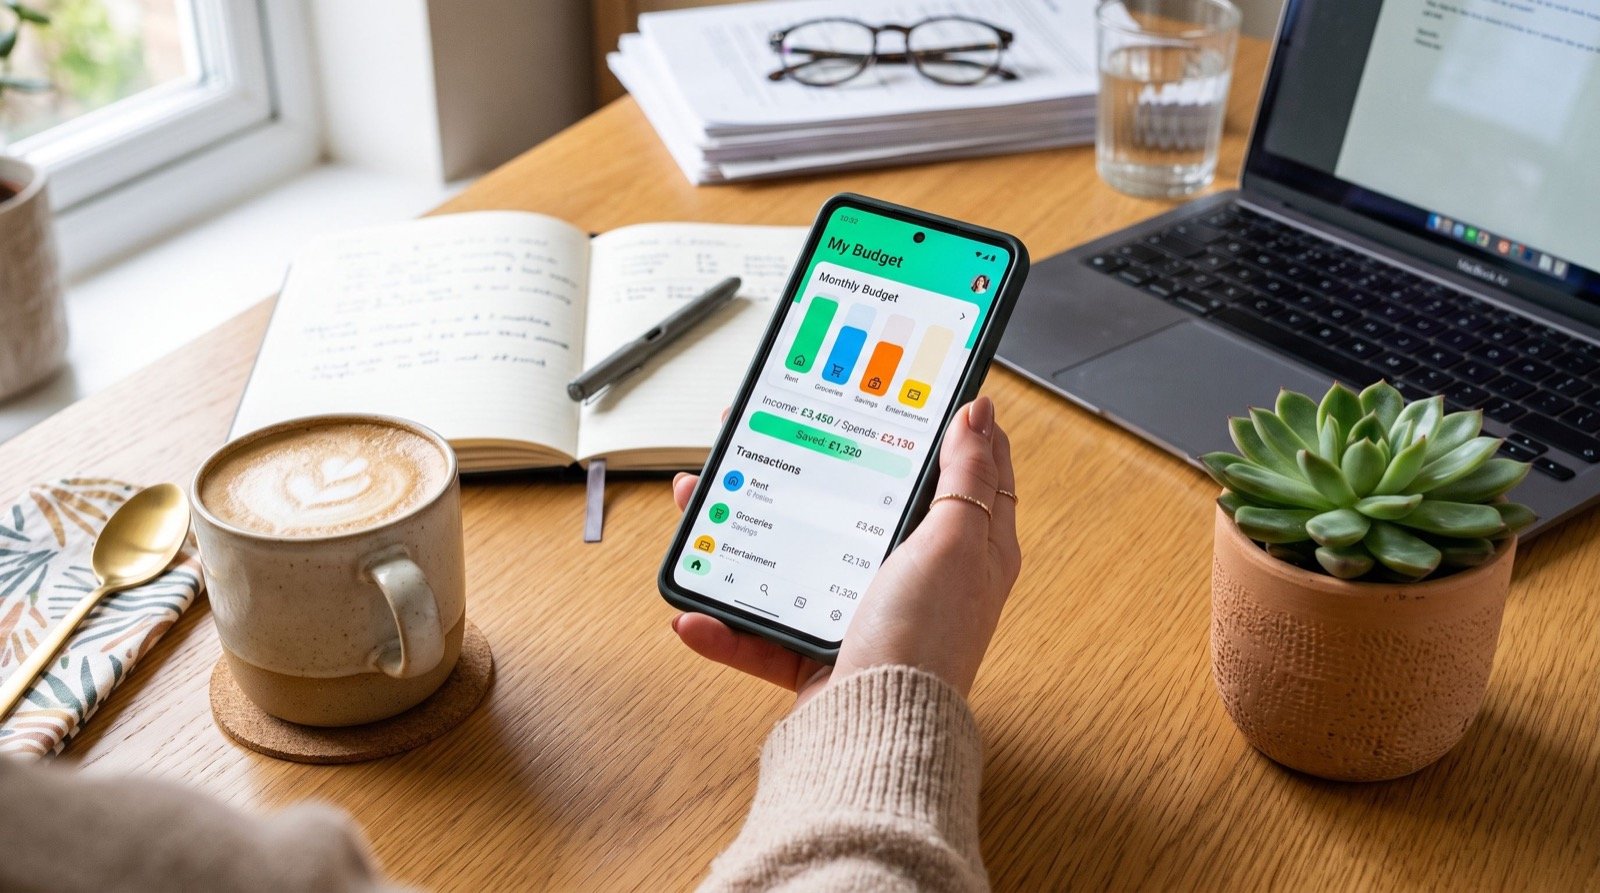
Apps can reduce the friction of money management, but they should support your plan, not replace it. Payment tools are especially common, and our Cash App guide explains how to use one safely for everyday transfers.
Whatever you use, apply these rules:
- Lock the app with a PIN or biometrics.
- Do not keep large balances in payment apps.
- Check every notification, and report unfamiliar activity quickly.
- Review subscriptions monthly and cancel the ones you forgot.
How Do You Stay Consistent After the First Month?
Consistency is where most plans quietly die. The first month feels exciting, and the third month feels like routine. Build in a few anchors so the routine survives.
- Pick a fixed weekly “money hour”, such as Sunday evening, and keep it short.
- Track only three numbers: savings balance, total debt, and what is left to spend this month.
- Celebrate milestones with a small, planned reward that is already in the budget.
- Tell a trusted friend or partner your goal so someone can ask how it is going.
If you miss a week, do not restart from zero. Open your statements, update your numbers, and continue. Progress in personal finance is rarely a straight line, and a plan that tolerates messy weeks is the plan that lasts.
Adjusting for irregular income
If your pay changes month to month, budget from your lowest typical month and treat anything above it as bonus money. Send the extra to savings or debt first, then to goals. This approach keeps essentials covered during slow periods and turns good months into real progress.
Small Habits That Compound
Once the foundation is laid, tiny habits make a visible difference over a year. Try a few of these:
- Wait 48 hours before any non-essential purchase above a set amount.
- Round up your monthly savings transfer whenever your pay increases.
- Review insurance and phone plans once a year for cheaper options.
- Use a separate account for fun spending so that the main budget stays clean.
A real-world example: a household that redirects a $40 monthly subscription cleanup into savings has $480 more at year-end, before any interest. It is not dramatic, but it is real and repeatable.
Frequently Asked Questions
What is the first thing to do with a paycheck?
Cover essentials and move a set amount to savings before anything discretionary. Automating that transfer removes the temptation to skip it.
Should I pay off debt or save first?
Build a small starter emergency fund first, then attack high-interest debt aggressively. A cushion prevents you from borrowing again when surprises appear.
How often should I review my budget?
Do a quick check weekly and a deeper review monthly. Adjust categories when your income or expenses change.
Do I need a financial advisor?
Not for the basics. Consider one for complex situations such as taxes, business income, or retirement planning with large balances.
Wrapping Up
Strong personal finance tips come down to knowing your numbers, automating savings, paying debt in order, and reviewing regularly. Pick one step this week and finish it. If you also need dependable help outside of money, an experienced local team can take pressure off the big life projects, like moving, so your budget stays on track.